Industrial Router Market Set to Reach $4.08 Billion as Wireless Upgrades Expand
- Satyajit Sinha
- 965 reads
Industrial router and access point revenue is forecast to reach $4.08 billion by 2030, with mobile automation and 5G shaping demand.
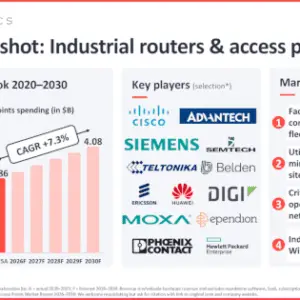
Industrial wireless spending is projected to reach $4.08 billion by 2030, as manufacturers and infrastructure operators connect more mobile equipment, extend networks to remote sites and replace aging hardware. IoT Analytics puts market revenue at $2.86 billion in 2025 and forecasts $3.11 billion in 2026, followed by a 7.3% compound annual growth rate through 2030. Growth is slower than the 9% recorded from 2020 to 2025, but the forecast period adds more revenue: $1.21 billion, compared with $1.03 billion over the earlier five years.
Unit shipments are expected to rise from 4.6 million in 2025 to 6.6 million in 2030. The blended average selling price is forecast to stay close to $620, with a cumulative increase of just 0.5% over that span. The market figures cover wholesale hardware revenue. They exclude IoT gateways, industrial Ethernet switches, firewalls, private 5G infrastructure, software and services.
Mobile equipment changes network demand
Factories and warehouses are adding automated guided vehicles (AGVs), autonomous mobile robots (AMRs) and other mobile assets. Each needs reliable wireless coverage and onboard connectivity, but access hardware demand doesn’t simply rise in proportion to robot installations. Coverage requirements, network topology and the number and movement of wireless endpoints all shape how many access points and related devices a facility needs.
Cisco is extending wireless capabilities used in enterprise networks to industrial mobility. In an April 2026 webinar, the US network hardware company demonstrated its Ultra-Reliable Wireless Backhaul (URWB) technology on its IW9165 and IW9167 access points, as well as selected enterprise Wi-Fi 6, 6E and 7 models. The approach lets a shared wireless infrastructure serve conventional Wi-Fi clients and moving equipment such as AGVs and forklifts, using common network management tools. It also puts Cisco into closer competition with established operational technology networking suppliers.
Remote sites and redundancy add hardware
Utilities, rail networks, ports and mining operations need rugged connections across geographically dispersed sites and mobile assets. Network extensions, new locations and resilience requirements can all add routers and wireless links. For transport equipment, those connections must also tolerate the operating environment and meet the relevant equipment requirements.
Teltonika Networks introduced its first 5G transport router, the ATRM50, in July 2025. The Lithuania-based company designed it to connect onboard equipment in rail and other transport vehicles to external networks. Its stated specifications include 5G connectivity, EN 50155 and EN 45545 rail certifications, and an operating temperature range of -40°C to 75°C. The product illustrates how cellular connectivity needs to extend beyond fixed industrial sites.
Redundancy can multiply equipment at a single site. In a European energy distribution modernization involving more than 1,000 existing-site migrations and more than 4,000 new sites, the operator selected Taiwan-based Advantech’s ICR-2431 LTE router. Standard sites use dual-SIM routers for network redundancy. At critical locations, the design uses two LTE routers on separate mobile networks in hot-standby mode, with satellite connectivity as a third backup path. The example shows how resilience requirements can raise hardware demand beyond the primary connection.
Wi-Fi 6/6E leads WLAN replacements; 5G lifts cellular revenue
Industrial users are moving to newer Wi-Fi and cellular generations, though the transition looks different in each segment. Wi-Fi 6/6E and Wi-Fi 7 together are forecast to account for 79.1% of industrial Wi-Fi revenue in 2030, up from 40.4% in 2025. Wi-Fi 6/6E alone is expected to contribute nearly 70% of 2030 revenue; Wi-Fi 7 is projected at about 9%. That points to Wi-Fi 6/6E as the main WLAN replacement generation through the forecast period.
Cellular revenue is shifting toward higher-value 5G and RedCap equipment. Those categories are forecast to make up 59.2% of industrial cellular revenue in 2030, while 4G/LTE is still expected to represent about half of cellular shipments. Higher-priced 5G/RedCap routers can therefore increase revenue faster than unit volumes. Across the whole market, Wi-Fi is forecast to account for roughly 75% of incremental shipments, while the cellular mix contributes disproportionately to revenue growth.
The underlying market tracker covers revenue, shipments and average selling prices for Wi-Fi 4, 5, 6/6E and 7, and for 4G/LTE and 5G/RedCap, with forecasts through 2030. The report also segments results by vendor, region and industry vertical.
Compatibility could shape upgrade decisions
New access points and routers generally need less memory than industrial PCs and compute-heavy gateways, which may limit their exposure to memory-price increases. IoT Analytics’ forecast of a 0.5% cumulative rise in blended average selling price from 2025 to 2030 suggests that pricing pressure alone may not define the upgrade decision.
The harder question may be whether older operational technology devices can stay connected as IT teams adopt newer Wi-Fi generations and security standards such as WPA3. A wireless upgrade has to serve installed equipment as well as new clients. Backward compatibility and interoperability across vendors may consequently carry as much weight in purchasing decisions as peak wireless performance. For engineers planning replacements, the useful signal is the installed device mix: newer access hardware can improve network capability, but the migration has to account for legacy endpoints that still need reliable access.
The forecast describes a market growing through several overlapping needs: mobile connectivity on factory floors, rugged links across distributed operations, redundant paths at critical sites and replacement cycles for aging wireless equipment. The shipment increase to 6.6 million units by 2030 will be driven largely by Wi-Fi demand, while the shift to 5G/RedCap raises the value of cellular hardware. How well new networks accommodate existing industrial devices will help determine how quickly that equipment is replaced.


